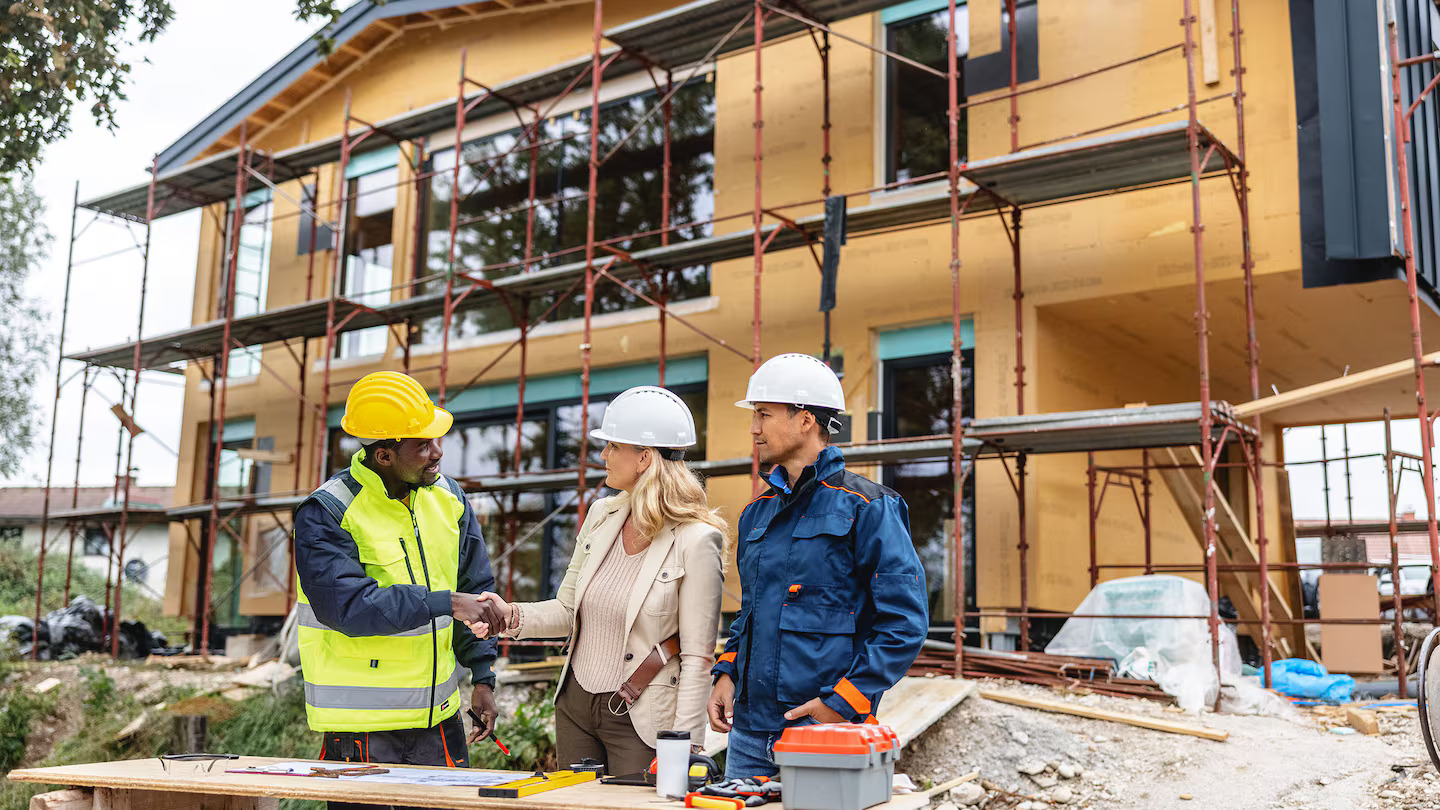
You weren’t planning to use your savings. Then the next construction draw got delayed!
Your farmer still wants payment on Friday, so now your savings are covering a bill you expected the loan to pay.
The loan covers the framing costs, but that doesn’t mean the money is available when your framer needs it. That’s because construction lenders release funds as the build reaches agreed stages, often after an inspector checks the completed work and the lender approves the draw. If either step takes longer than expected, the money may not arrive before Friday’s deadline.
That wait is easier to plan for when you know what the lender checks before releasing each draw and when the money is likely to arrive. This OMJ Mortgage guide explains how construction draws work from the early building stages through move-in day, including:
- What construction draws are and why lenders use them
- How draws differ from a regular or completion mortgage
- How a draw schedule works
- The six building stages covered in this guide and when draws may be released
- When builders actually receive their money
- What can delay a draw and affect your cash flow
- How to prepare for smoother draws
What Are Construction Loan Draws and Why Do Lenders Use Them?
Construction loan draws (also called progress draws or advances) are payouts that release your approved loan in parts as the build moves forward. Lenders use them because a half-built house has weak security. If they paid out the whole loan upfront and the project stalled, they’d be stuck with an unfinished property worth less than the money they’d handed over. So they only pay for work an inspector has checked.
This setup surprises a lot of first-time builders right after approval, and maybe you’re one of them.
“The bank approved your construction loan. So where’s the money?”
The loan agreement shows the full amount, but your account still shows nothing. Approval only sets the most you can borrow, and the lender then pays it out one finished stage at a time. That stage-by-stage payout is why many Canadian lenders call this kind of loan a progress draw mortgage, or simply a draw mortgage.
The same setup that protects the lender protects you as the borrower, too. You pay interest only on the money you’ve drawn (the FAQs below explain how that works), and no contractor gets paid for work that hasn’t happened yet.
That second point matters a lot more than it sounds. If a contractor collected the money for a whole stage upfront and then walked off the job, you’d end up paying a second crew to finish that same stage, on top of what the first contractor already took. Draws stop that from happening. That stage’s money stays with the lender until the work passes inspection, so it’s still there for whoever finishes the job.
How Is Construction Financing Different From a Regular or Completion Mortgage?
A traditional mortgage pays the full loan on closing day, while construction financing releases it in stages after each inspection. A completion mortgage works differently again, because the builder carries the cost of construction and your mortgage only funds once the home is finished. Here’s how the three compare on seven points.
| Feature | Construction loan draws | Completion mortgage | Traditional mortgage |
| How money arrives | In stages during the build | In one lump sum once the builder finishes the home | In one lump sum on closing day |
| What triggers payment | An inspector confirms a finished stage | The builder completes the home and the purchase closes | The sale closes and the title transfers |
| Interest | Applies only to the amount you’ve drawn | Starts once the mortgage funds at completion | Applies to the full balance from day one |
| Regular payments | Often interest-only until the final draw | Principal and interest from the first payment | Principal and interest from the first payment |
| Paperwork | A request, inspection, and title check for every draw | One set of closing documents | One set of closing documents |
| Best fit | Custom homes, infill, and condo projects (OMJ’s focus) | Buying a new home from a builder who finances the build | Buying an existing or completed home |
| Main tradeoff | You control the build but manage cash between draws | Simpler, but you buy what the builder offers, on the builder’s timeline | Simplest, but only for homes that already exist |
How Does a Construction Loan Draw Schedule Work?
A construction loan draw schedule shows how much of your approved financing the lender plans to release at each agreed building stage. OMJ Mortgage notes that new builds will often have up to seven draws. Reaching one of those stages doesn’t mean the money arrives immediately. The lender may still need to inspect the finished work and approve the draw before releasing the funds.
That approval may still be pending when your builder has finished one stage and lined up the next crew.
So, your house is ready for the next stage. Your construction loan isn’t.
To see why the build can move faster than the payments, look at the 5 parts that connect your builder’s plans to the lender’s release process:
- The total approved loan sets the overall funding limit, subject to the lender’s conditions.
- The construction budget shows how much each part of the build is expected to cost.
- The project timeline will show when your builder expects to complete each stage.
- The draw schedule ties the payments to agreed construction milestones and sets out how much can be drawn at each milestone.
- The inspection and approval process checks whether the completed work and draw request meet the lender’s requirements before funds are released.
How Are Construction Loan Funds Released at Each Building Stage?
Lenders release construction loan funds as work progresses, usually after checking that the required work is complete. The main stages are land preparation, foundation, framing, mechanical and electrical installation, interior finishing, and project completion. That’s the usual order, with some stages, of course, overlapping. The amount varies by lender and project, and not every stage triggers a draw. For a custom home, the breakdown could look like this.
| Stage | What happens at this stage | Typical draw and when it’s released |
| Land preparation | Starts with the survey and the necessary permits, then moves on to grading and digging for the foundation | May not receive a construction draw, since some lenders require the land purchase and early site costs to be funded separately |
| Foundation | Begins once the site has been excavated, with the footings and any basement walls put in place before waterproofing and backfilling, where necessary | May qualify for the first draw, around 10% to 15% of the loan, once the site is prepared and the foundation is completed and verified |
| Framing | Builds the floors, walls, and roof structure with the foundation in place | May qualify for another 15% to 20% once the floors, walls, and roof structure are built on the foundation |
| Building enclosure (lock-up) | Windows, exterior doors, and roofing close in the framed house at the end of framing | May release another 10% to 15% once windows, exterior doors, and roofing make the framed house weather-tight |
| Mechanical and electrical installation | Uses the open framing to run the plumbing, wiring, and ducting (ductwork) before the insulation goes in | May qualify for a 15% to 20% draw once the plumbing, electrical, and HVAC rough-ins are complete and the required inspections are cleared |
| Interior finishing | Comes after the inspection of those installations and the insulation has been put in place. That’s when the drywall is added, along with the flooring and all the fixtures you’ve spent weeks selecting | May account for another 20% to 25% after the rough-ins pass inspection, as drywall, flooring, cabinets, and fixtures are installed |
| Project completion | Covers a deficiency walkthrough, any remaining fixes, municipal sign-off (including the occupancy permit), and a final clean before move-in | May release the remaining approved loan funds once the finishing work, outstanding fixes, and lender requirements are complete |
The final draw doesn’t remove Ontario’s separate 10% construction lien holdback requirement, which follows its own release rules.
These percentages are only examples. Renovations and additions usually need fewer draws, since there are fewer stages to inspect.
A two-storey custom home and a 40-unit condo may need funds at different points in construction, so OMJ works out financing and draw schedules around each project.
If land costs fall outside the construction loan, OMJ can also help arrange separate land financing.
When Does Your Builder Get Paid From a Construction Loan Draw?
Builders can receive payment from a construction draw once the lender has checked the completed stage, reviewed the paperwork and released the approved funds. The time this takes varies by lender, so ask how long inspection booking, the inspector’s report, lender review and the fund transfer each take. The process generally follows these 5 steps:
- The builder finishes the stage and sends you an invoice, along with any required supplier and subtrade records.
- You send the draw request with that invoice and any photos or other records the lender asks for.
- The lender arranges a site visit by an appraiser or progress inspector, or a quantity surveyor on larger projects, to assess the completed work.
- Before funds are released, the lawyer handling the draw checks the title for any new construction liens.
- Once approved, the draw is released to you or your builder (less any required holdback and applicable fees). If the funds come to you, pay the builder.
If you manage the build yourself as an owner-builder and your lender allows it, the steps stay the same, but each trade, such as your framer, invoices you directly and you pay them from the draw.
Who decides when your builder gets paid: you, the bank, or the building inspector? The lender decides when to release the draw, while you remain responsible for paying the builder under your contract. To approve that release, the lender needs more than a passed city inspection. The city’s inspector checks the work against the building code and approved plans, while the lender’s inspector assesses how much work is complete to help determine the draw amount. The lender uses that assessment, along with the paperwork and title checks, to decide whether to approve the draw.
While you wait for that approval, the deadline for paying your builder may already be approaching. If your contract falls under Ontario’s Construction Act prompt-payment rules, you generally have 28 days from receiving a proper invoice to pay the amount due, subject to the required holdback. So if the draw funds arrive three weeks after you receive that invoice, you have about seven days left to pay. If you intend to withhold a disputed amount, however, you must give the builder a notice of non-payment in the prescribed form within 14 days of receiving the invoice, stating the amount and reasons.
How Do Construction Loan Draws Affect Project Cash Flow and Contractor Payments?
Construction loan draw timing determines when loan funds become available for materials and subtrade payments. If a draw arrives late or covers less than expected, you or your builder may need other funds to pay bills that are already due.
That gap can arise with material orders as the supplier may well require a deposit before ordering the windows or the custom cabinets. If that deposit falls due before the lender will fund that part of the work, you and your builder need to plan how it will be paid.
Alongside those deposits, your builder also has subtrade bills to pay. Where Ontario’s prompt-payment rules apply, builders generally have seven days after receiving payment to pay the subtrades covered by that payment. If you pay late, your builder still has payment deadlines and notice requirements to follow. Without enough cash to meet those obligations, your builder may struggle to keep crews on schedule.
Even if a draw comes in on time, the amount released may be less than what your builder has asked for in framing. Your builder needs $40k. The bank releases $25k. Who pays the difference?
In this example, $28,000 of the $40,000 request relates to completed work. Assume the lender funds that amount before deducting the holdback and inspection fee:
| Framing draw calculation | Amount |
| Builder’s framing funding request | $40,000 |
| Verified completed work eligible for this draw | $28,000 |
| Less the 10% holdback | −$2,800 |
| Less the inspection fee | −$200 |
| Amount the lender releases | $25,000 |
| Difference from the amount requested | $15,000 |
That $15,000 consists of $12,000 for work not yet completed, a $2,800 holdback and a $200 fee. The unfinished work may qualify for a later draw once completed and approved, while the inspection fee is an expense that will not be released later. You usually pay that fee for every draw, and your mortgage documents should list it.
The amount you’ll need to cover at this stage will depend on what’s actually payable under your contract. For bills due before the further release of loan funds, you may need to have savings or agreed financing in place. If your builder is prepared to take on some of the costs in the interim, that arrangement should be put in place now, with the required holdback still in place.
The Ontario Construction Act generally sets that holdback at 10% of the price of services and materials supplied. The date of release will be in accordance with the relevant lien and holdback rules. For instance, the 60-day lien period may commence upon the publication of the substantial performance certificate, so completion of the work in itself will not necessarily be the trigger for release. The annual holdback release rules effective January 1st 2026, may also have an impact on the timing of release, subject to the applicable notice requirements and transition rules for pre-existing contracts. These rules apply in Ontario; other provinces set their own holdback and payment rules.
To plan for these gaps, OMJ includes holdbacks and fees in your financing plan from the start. If additional funding is needed, it can assess whether a private construction loan or, for a development project, mezzanine financing is suitable, subject to the existing lender’s terms.
What Can Delay a Construction Loan Draw, and How Can You Prevent It?
Construction loan draw approval can slow down if the lender can’t verify the work is complete, can’t get the required documentation, or can’t confirm sufficient funds are available to finish the job. Until the issue is resolved, the lender may well be in a position to delay the draw or to release less than you’ve asked for. You can smooth the draw process by properly budgeting each stage, having all the paperwork ready and maintaining a cash pot outside of the loan.
Waiting for that payment can be quite the pain when the walls are up and you can see your dream home taking shape, but of course, you can’t move ahead. To get the draw going again, you have to know what the lender is waiting for:
| Delay | Why the draw slows down | How to prevent it |
| Unfinished work | The lender may reduce or delay the draw if the completed work falls short of the agreed milestone. | Agree on draw milestones with the lender so each request corresponds to completed work the inspector can verify. |
| A failed city inspection | The lender may need evidence that the crew has corrected the problem before releasing funds. | Allow time for inspections and lender processing, and book the city inspection before you request the draw. |
| A budget overrun | The lender has to confirm how the extra costs will be covered so that there are sufficient funds to complete the house. | Budget each stage separately, with a clear cost breakdown to support the draw request. Keep a contingency reserve outside the loan to help cover unexpected costs, and confirm with the lender whether 10% of the build budget is enough for the project. |
| Missing invoices | Without required invoices or supporting records, the lender may be unable to verify the amount requested. | Keep invoices, permits and inspection reports together, ready to provide when the lender asks for them. |
| A contractor dispute | If a dispute results in a registered construction lien, further draws will be held up until the lien is discharged or otherwise dealt with to the lender’s satisfaction. | Coordinate contractor payment dates with the draw schedule, so your builder is paid on time. |
| A change in scope | Adding a room or changing the plans may require a revised budget and lender approval prior to the extra work being funded. | Tell the lender about budget or schedule changes early, giving them time to review the effect on the next draw. |
Increasing construction costs can contribute to a budget overrun: Statistics Canada reported that residential building construction costs rose 2.7% year over year in Q3 2026 across its composite of 15 metro areas, though Toronto’s quarterly increase of 0.4% was among the smallest.
When you’re setting up the loan, OMJ will check for incomplete records and a contingency that leaves too little room for any additional costs. That way, any budget or paperwork problems can be addressed early.
Explore How Construction Loan Draws Fund Your Custom Home Build
Construction loan draws fund your build in stages, with progress payments generally tied to verified work and lender approval. Your builder’s bills may be due before the funds have actually arrived so it’s important to plan around inspections, holdbacks, and payment dates to work out how much cash to keep available.
That planning is where OMJ comes in. The Markham-based brokerage arranges construction loans for custom homes and larger developments across the GTA and can review how the lender’s draw schedule fits your builder’s payment needs. If that review reveals a funding gap, the team can also assess whether land, bridge or private financing could help cover it.
Review your draw schedule with OMJ before your builder pours the foundation, so you can plan how to cover the early construction bills.
Frequently Asked Questions (FAQs)
Q1. How much cash do I need before my first construction loan draw?
The amount of cash you’ll need will be determined by the lender’s equity requirement and the bills you have to pay prior to your first draw. Although a standard home purchase at or above the Department of Finance’s $1.5 million insured mortgage cap will typically require at least 20% down, a construction lender may require more equity. You need to confirm that requirement and whether or not the land you already own counts towards it.
Then check which land costs and construction bills will fall due before the first draw, and how much of those costs other approved financing will cover. If that draw comes at foundation stage, plan how to fund the early work until those funds are released.
Q2. What if my construction loan draw isn’t enough to pay my builder?
If a draw falls short, ask the lender what caused the gap before deciding how to cover it. When funds are delayed, you may need to use savings or agree on a later payment date with your builder. If the delay is due to unfinished work, confirm what the lender needs completed before releasing the delayed funds.
A budget overrun needs a different response because it increases the total cost of the build. In that case, the next scheduled draw may still leave a shortfall, and additional borrowing will need lender approval.
Q3. Do I pay interest on the full construction loan or only the amount I’ve drawn?
You generally pay interest only on the amount drawn, so the interest charge usually rises as more funds are released. Many construction loans require monthly interest-only payments during the build. With private financing, check whether those interest charges can be added to the loan balance instead of paid monthly.
Q4. What happens to my construction loan after the final draw?
Once construction is complete, your loan may convert into a regular mortgage or be repaid through a separate take-out mortgage. With construction-to-permanent financing, that conversion depends on meeting the lender’s completion and mortgage conditions.
For a stand-alone or private construction loan, the agreed maturity date sets the repayment deadline, so any take-out mortgage must be ready to fund by then. An open building permit can also delay the take-out mortgage, so book the final inspection to close the permit before you refinance.